

August 27, 2026
article by the prompt team
Are you feeling the pressure of rising costs and an increasingly demanding market? Here are five practical tips to help secure your business through uncertain times and give you greater financial flexibility.
Economic uncertainty, fluctuating interest rates, and increased operating costs are realities that many small and medium-sized businesses in Ghana must contend with right now. When margins are squeezed, financial flexibility becomes the key to adapting well and making sound decisions — even under pressure.
The good news is that in the face of change and unpredictability, small steps can have a big impact. By making deliberate adjustments to your finances, strengthening your visibility into your numbers, and leveraging the right digital tools, you can build a more resilient business and create genuine room for growth — even when times are tough.
Here are five specific pieces of advice from the Prompt Integrated team that can give you better control, increased room to manoeuvre, and a more secure financial foundation — not just for today, but for the long term.
Here’s what we’ll cover:
- Review your invoicing routines
- Get a clear picture of your business’s liquidity
- Identify costs you can cut
- Talk to suppliers and creditors early
- Build a financial buffer for flexibility
- Final thoughts
1. Review your invoicing routines
The fastest way to improve your cash flow without changing a single thing about your product or service is to get paid faster — and that starts with your invoicing process.
Take a careful look at how you currently invoice your customers. Are your payment terms as tight as they reasonably can be? If you are currently giving customers 30 days to pay, could you move to 14 or even 7 days for certain clients? Even a modest reduction in your payment window can make a meaningful difference to your cash position across the course of a month.
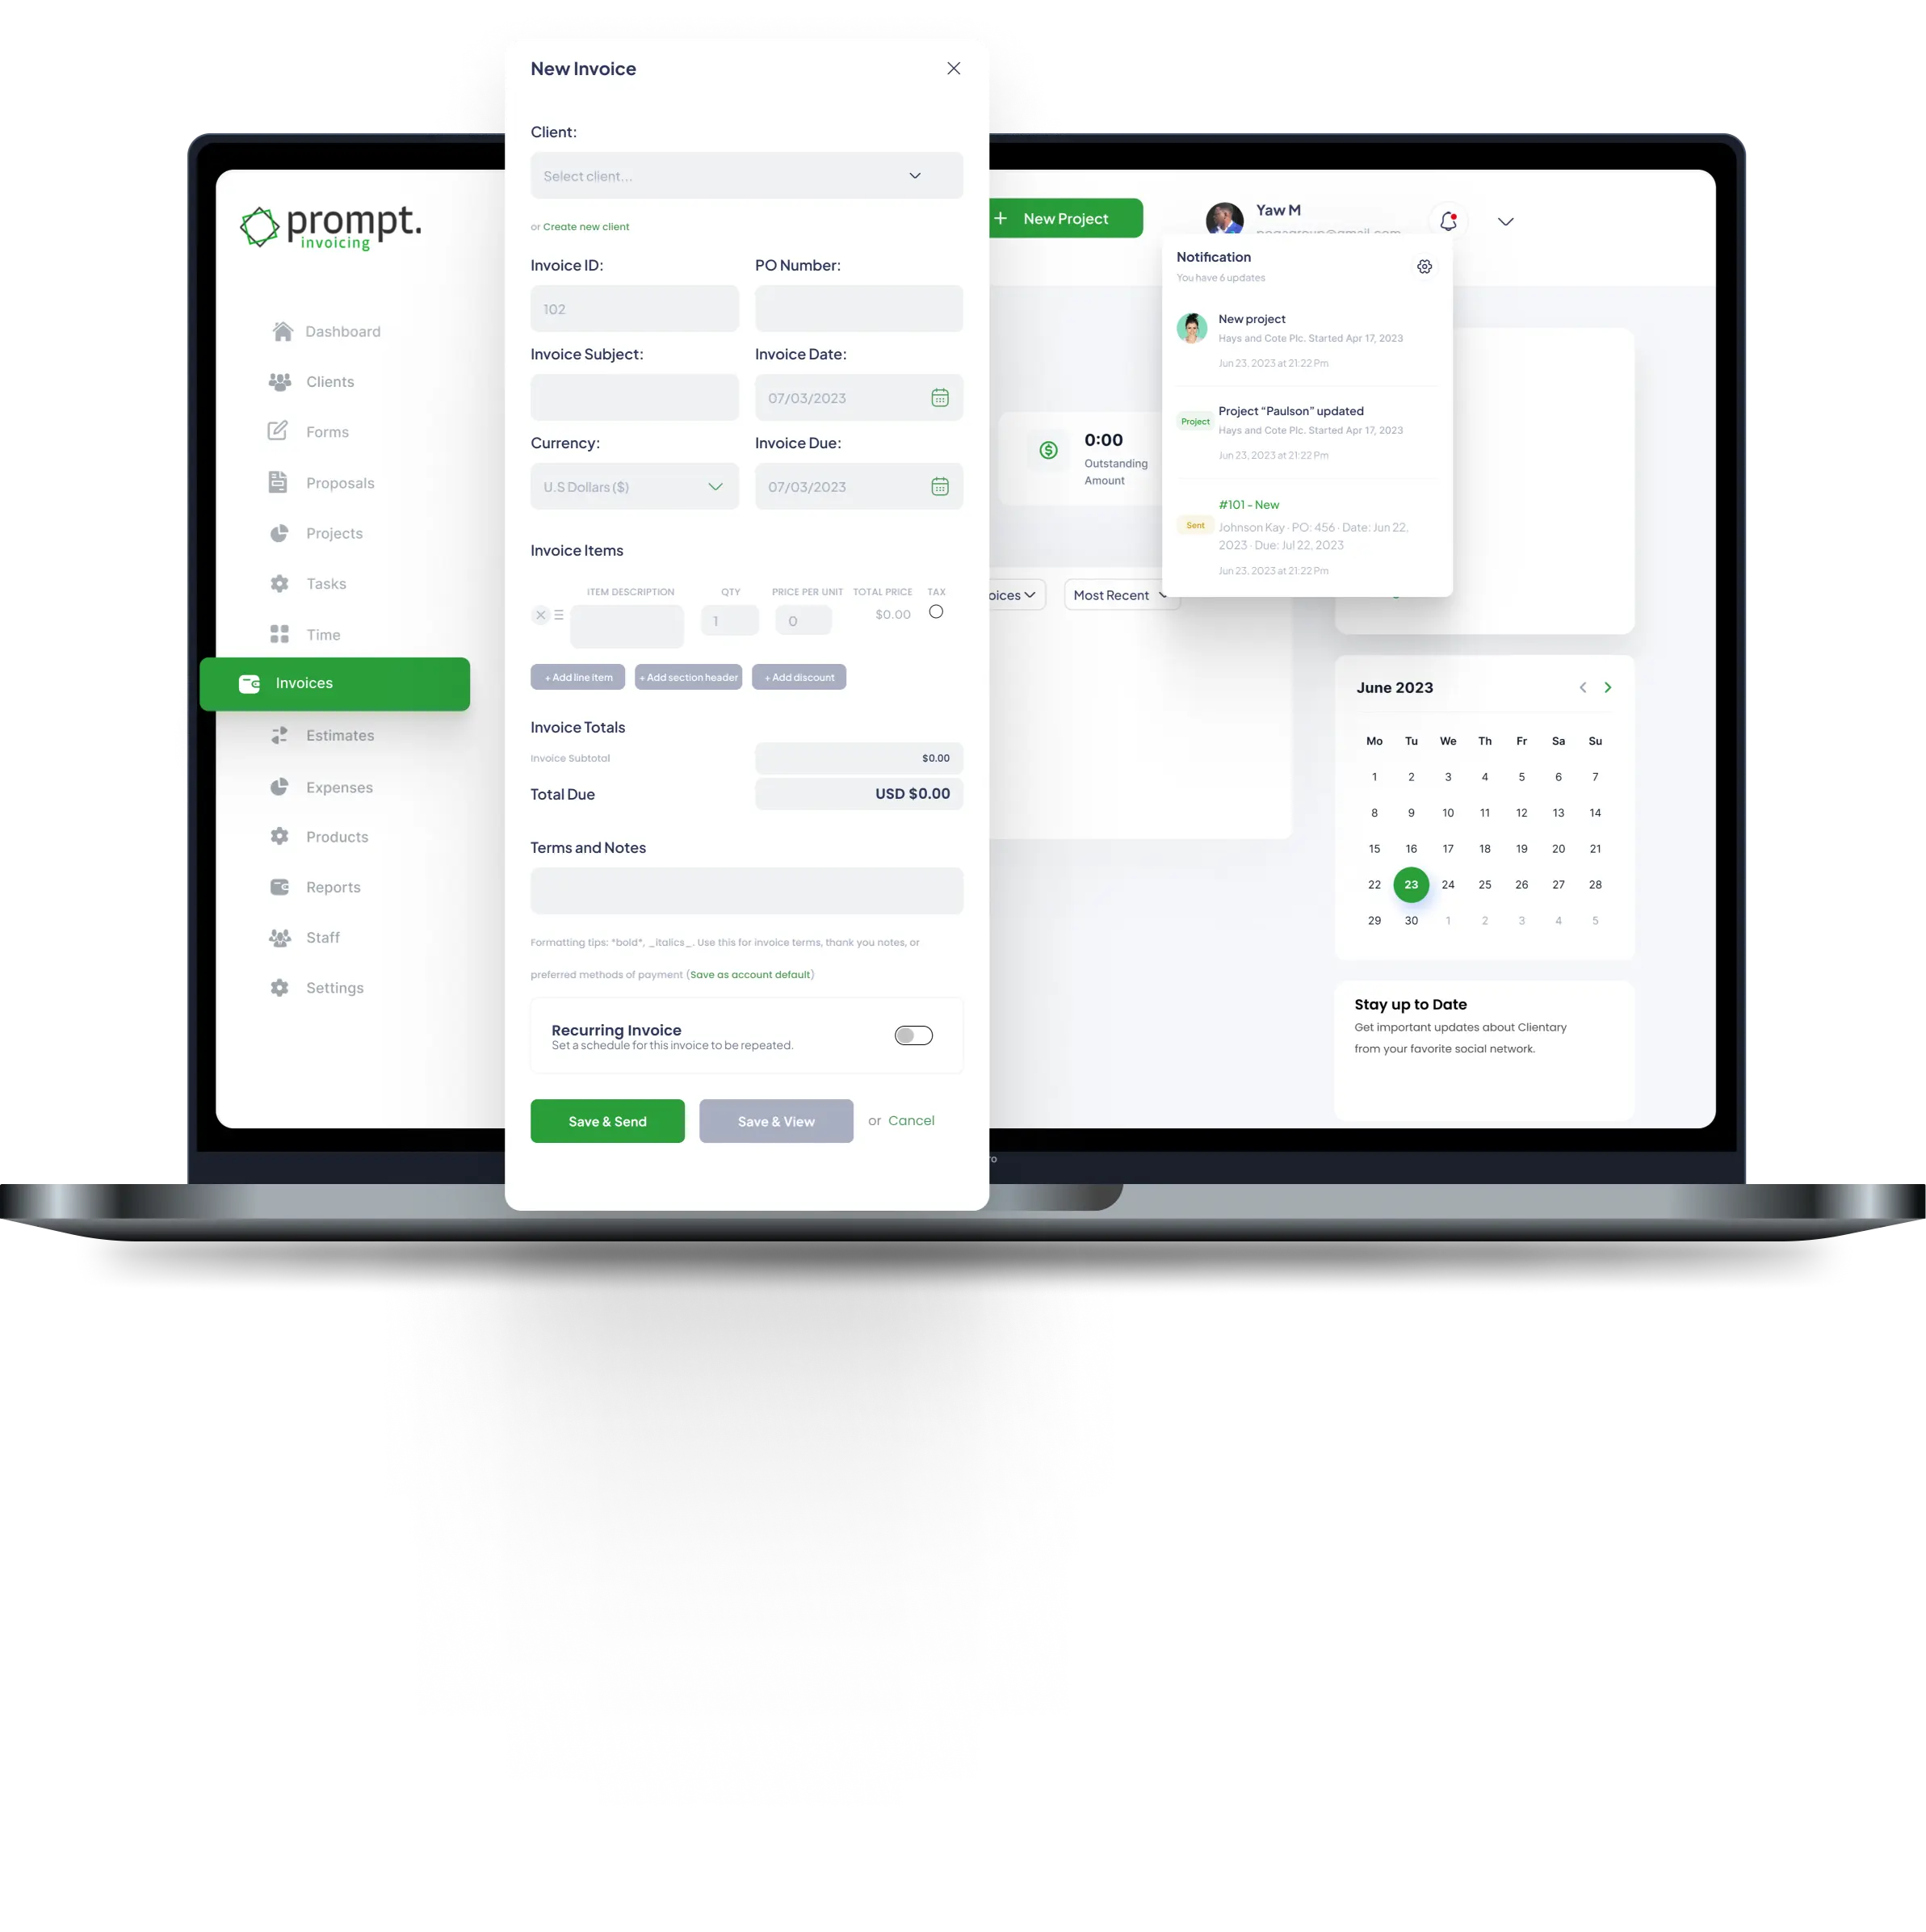
Consider also how your invoices are being sent and received. Manual invoicing processes — through WhatsApp, email attachments, or printed documents — introduce delays and the risk of invoices being lost, missed, or deprioritised. Digital invoicing, where the invoice arrives instantly and includes a direct payment link, removes most of that friction and significantly reduces the time between invoicing and payment.
In Ghana’s mobile-money-first environment, giving customers the option to pay directly via MTN MoMo from the invoice itself is one of the most effective ways to accelerate collections.
At the same time, consider negotiating longer payment terms with your own suppliers wherever possible. Extending the time you have to pay while shortening the time it takes to collect creates a healthier cash flow gap — and that gap is where financial flexibility lives.
2. Get a clear picture of your business’s liquidity
Do you have genuine visibility into your business’s liquidity — the cash available to meet your obligations at any given moment? If not, establishing that visibility should be a priority right now.
A liquidity budget — a forward-looking view of your expected cash inflows and outflows over the coming weeks and months — is one of the most valuable tools a small business owner can have during uncertain times. It shows you not just where you are today, but where you are likely to be in 30, 60, or 90 days — and that early warning is what gives you time to act before a problem becomes a crisis.
If you can see a cash flow shortfall approaching two months from now, you have time to address it — by accelerating collections, deferring non-essential spending, negotiating extended supplier terms, or arranging a credit facility. If you only discover the shortfall when it arrives, your options are far more limited and far more stressful.
3. Identify costs you can cut
Cutting costs is never pleasant. But in a period of economic pressure, it can be exactly what keeps a business operational — and it is almost always better to make deliberate, strategic cuts early than to be forced into desperate measures later.
Start by reviewing every current cost in your business with a clear, objective eye. For each one, ask a simple question: is this cost directly contributing to revenue or to a goal that matters right now? If the answer is no — or even maybe — it is a candidate for reduction or elimination.
Common areas where Ghanaian small businesses find unnecessary spending include unused software subscriptions, supplier arrangements that have not been renegotiated in years, spending on marketing channels that are not generating measurable returns, and operational habits that made sense at an earlier stage of the business but no longer deliver proportionate value.
Beyond cutting costs, also consider whether your revenue can be increased without significant additional investment. Are your prices set at the right level given current market conditions and your own cost increases? Are there products or services in your offering that consume significant time and effort but generate relatively little income? Redirecting that time and energy toward higher-margin activities is a cost-cutting measure in a different form.
4. Talk to suppliers and creditors early
If you can see that a difficult period is coming — that you may struggle to meet a supplier payment or service a debt on time — the single most important thing you can do is start that conversation early.
This is counterintuitive for many business owners, who prefer to hope the situation resolves itself rather than alert a supplier or creditor to a potential problem. But early, open dialogue almost always produces better outcomes than silence followed by a missed payment.
Suppliers and creditors who are approached proactively — with honesty about the situation and a clear proposal for how it will be managed — are significantly more likely to cooperate, offer extended terms, or find a mutually workable solution. The same creditor who might take firm action over a missed payment with no prior communication is often willing to be flexible with a business owner who has maintained an open and organised dialogue.
At the same time, it is worth reviewing whether better terms are available elsewhere. Are there alternative suppliers offering comparable quality at lower cost or with more favourable payment conditions? Exploring your options, even when you are not in immediate difficulty, is simply good business management.
5. Build a financial buffer for flexibility
Many businesses experience periods of poor liquidity — it is a normal feature of running a business rather than a sign of failure. Seasonal fluctuations, delayed client payments, unexpected costs, and sudden changes in market conditions can all create temporary cash flow gaps that even well-managed businesses encounter.
The difference between a business that navigates those gaps smoothly and one that is thrown into crisis by them is almost always the same thing: preparation.
Having a financial buffer — whether that is cash reserves built up during stronger periods, an arranged overdraft facility with your bank, or access to a revolving credit line — gives you the flexibility to handle short-term liquidity challenges without making reactive, costly decisions under pressure.
In Ghana, several commercial banks and microfinance institutions offer working capital and overdraft facilities specifically designed for SMEs. The Ghana Association of Savings and Loans Companies represents many of the deposit-taking institutions that serve small businesses across the country — and exploring their products before you need them is significantly better than approaching a lender at the moment of crisis.
Building that buffer starts with accurate financial management. Prompt Integrated has created a template for setting up a liquidity budget.
Final thoughts
Economic uncertainty is not unique to any one period or any one market — it is a recurring feature of business life that every entrepreneur eventually has to navigate. The businesses that come through difficult periods strongest are not always the ones with the deepest pockets. They are the ones with the clearest financial visibility, the most disciplined habits, and the right tools in place to respond quickly when conditions change.
The five steps covered in this article — tightening your invoicing, monitoring your liquidity, reviewing your costs, communicating early with creditors, and building a financial buffer — are all within reach of any Ghanaian small business owner willing to take them seriously.
Start with the one that will make the biggest difference to your situation right now. Build the habit. Then move to the next.
Prompt Integrated is built to support exactly this kind of financially disciplined, resilient Ghanaian small business — with invoicing, expense management, payroll, and project management all in one affordable, cloud-based platform. Get started with Prompt Integrated today.


Leave A Comment