

October 07, 2026
article by the prompt team
Is your business growing — but is your financial management keeping up with it?
Many Ghanaian entrepreneurs build strong early momentum through hard work, good relationships, and a sharp instinct for their market. In the early days, it is possible to keep most things in your head: who your customers are, what your costs look like, which projects are running well, and where the money is going.
But as the business grows — more employees, more projects, new managers, new clients — that mental overview starts to break down. And the financial follow-up often stays the same as it was when the business was smaller, even though the questions that matter have changed completely.
It is no longer enough to know that the accounts are being kept, the salaries are going out, and the deadlines are being met. The questions a growing Ghanaian business needs answers to are different: Which projects are actually making money? Why are margins falling when sales are increasing? Which customers should you be prioritising? How much growth can your current liquidity actually handle?
Good financial management in a growing business is about being able to answer those questions while you still have time to act on the answers.
Prompt Integrated’s product development team shares four of the most common financial management mistakes that growing Ghanaian businesses make — and what to do about each one before it becomes costly.
Here’s what we’ll cover:
- Making decisions before the numbers are clear
- Tracking sales instead of profitability
- Planning for growth but not for liquidity
- Stopping at the report
- Where business leaders should start
- Final thoughts
1. Making decisions before the numbers are clear
Picture a typical scenario: the management team is sitting down to discuss a new hire or a significant investment. The latest financial report is not ready yet — it will be available next week. So the discussion continues, decisions are made, and commitments are considered — based on information that is already out of date.
This is one of the most common and most costly financial management mistakes that growing businesses make. Costs may have increased since the last report. A project that looked profitable a month ago may have turned. Invoicing may have stalled without anyone noticing. But because the numbers are not current, none of that is visible in the room when the decision is made.
How to take action: Agree as a leadership team on exactly which figures you need before any significant management discussion — and who is responsible for having them ready, and by when. Set a clear deadline: the numbers need to be available before the meeting, not the week after it.
This also requires consistent routines throughout the business. Employees must record their hours accurately and on time. Managers must review and approve invoices promptly. Costs must be captured correctly in the system as they occur. A good accounting and financial management system makes information available — but the data inside it is only as good as the discipline that feeds it.
It is also worth being clear about the distinction between an ongoing, real-time overview and a fully reconciled monthly figure. Both are valuable, but they serve different purposes. Everyone using financial reports should know where to find the most current data and what may still be missing from it.
2. Tracking sales instead of profitability
A large customer generating high turnover feels like a success. But that same customer may require constant follow-up, frequent revisions, and many additional hours that are never invoiced. If you are only looking at total revenue, that picture is invisible.
Growing businesses in Ghana can fall into the trap of selling more while actually becoming less profitable — because they are scaling the products, services, and customers that generate the least margin, without realising it.
How to take action: Choose a small number of key metrics that genuinely explain the profitability of your specific business — not just the revenue it generates. For a consulting or professional services business in Ghana, this might be the billable rate per project and the margin after time costs are accounted for. For a trading business, it might be the contribution margin per product category and how long inventory is held before it is sold.
Make sure your revenue and costs are recorded in a way that allows you to track these metrics accurately. And agree across the business on how those numbers are calculated — because if your sales team and your finance function arrive at the same management meeting with different answers about what a profitable client looks like, the discussion that follows will be confused rather than productive.
This clarity gives you a much stronger basis for making decisions about pricing, capacity, and which work you should and should not be taking on as you grow.
3. Planning for growth but not for liquidity
A profitable business is not the same as a cash-flow-positive business — and in Ghana’s often challenging payment environment, where client payment terms can stretch and invoice collection can be slow, this distinction matters enormously.
Consider a common scenario for a growing Ghanaian business: you win a significant new contract. To deliver it, you need to hire, purchase equipment or materials, and pay your suppliers — all before the client pays you. The contract is profitable in the long run. But in the short term, it creates a period of tight liquidity that, if not planned for, can create serious operational pressure.
The business is growing. The books look good. But the cash is not there when it needs to be.
How to take action: Create a liquidity budget that runs alongside your growth plan — projecting expected cash inflows and outflows week by week or month by month. Include salaries, tax obligations to the Ghana Revenue Authority, SSNIT contributions, planned investments, and realistic assumptions about when your clients will actually pay.
Then stress-test it. What happens if a major client pays 30 days later than expected? What happens if you need to hire earlier than planned? When you map these scenarios in advance, you have time to adjust your payment terms, defer a non-essential investment, or arrange a credit facility before the pressure arrives — rather than scrambling to respond after it does.
4. Stopping at the report
The financial report goes out. Someone reads it. And then everyone moves on to the next task.
This is perhaps the most subtle of the four mistakes — because it can happen even in businesses with good financial systems and well-prepared reports. The data is there. The numbers are accurate. But if no one investigates the deviations, agrees on what they mean, and commits to specific actions in response, the report has no real impact on how the business is run.
If profitability is declining, you need to understand why. Is it a pricing issue? Are more hours being spent on projects than are being invoiced? Have purchasing costs increased? Have you shifted toward a client mix that is generating lower margins? A report can tell you that something has changed. Only investigation can tell you what to do about it.
How to take action: Set aside dedicated time — regularly, not occasionally — to review your financial position with someone who can help you interpret what the numbers are saying. This might be your finance manager, your external accountant, or a trusted business advisor. The goal is not just to confirm that the numbers have been reviewed, but to leave every session with concrete decisions: what needs to change, who is responsible for making it happen, and when you will review the effect.
For Ghanaian small businesses without a dedicated finance department, a regular advisory relationship with a qualified accountant from the Institute of Chartered Accountants Ghana can serve this function — providing the analytical support and interpretive expertise that turns financial data into actionable decisions.
Where business leaders in Ghana should start
The most practical starting point is a decision you need to make soon.
Are you considering hiring a new team member? Adjusting your pricing? Entering a new market in Ghana or beyond? Start by identifying exactly which numbers you need to make that decision well — and then check honestly whether you have access to those numbers today.
If you do not, that gap is where your financial management needs the most immediate attention.
The Prompt Integrated team is available to help Ghanaian businesses set up reporting structures that give leadership the right information at the right time — tailored to the specific decisions your business needs to make as it grows.
Final thoughts
Growth is exciting. But growth without financial control is fragile — and the businesses that scale successfully in Ghana are almost always the ones that invest in financial management disciplines early, before the gaps in their oversight become expensive problems to fix.
The four mistakes described in this article — making decisions on outdated numbers, tracking revenue instead of profitability, planning for growth but not for liquidity, and treating the report as the end of the process — are all avoidable. They require clarity, consistency, and the right tools to address. But addressing them is what separates businesses that grow sustainably from those that grow fast and then struggle to understand why the results do not reflect the effort.
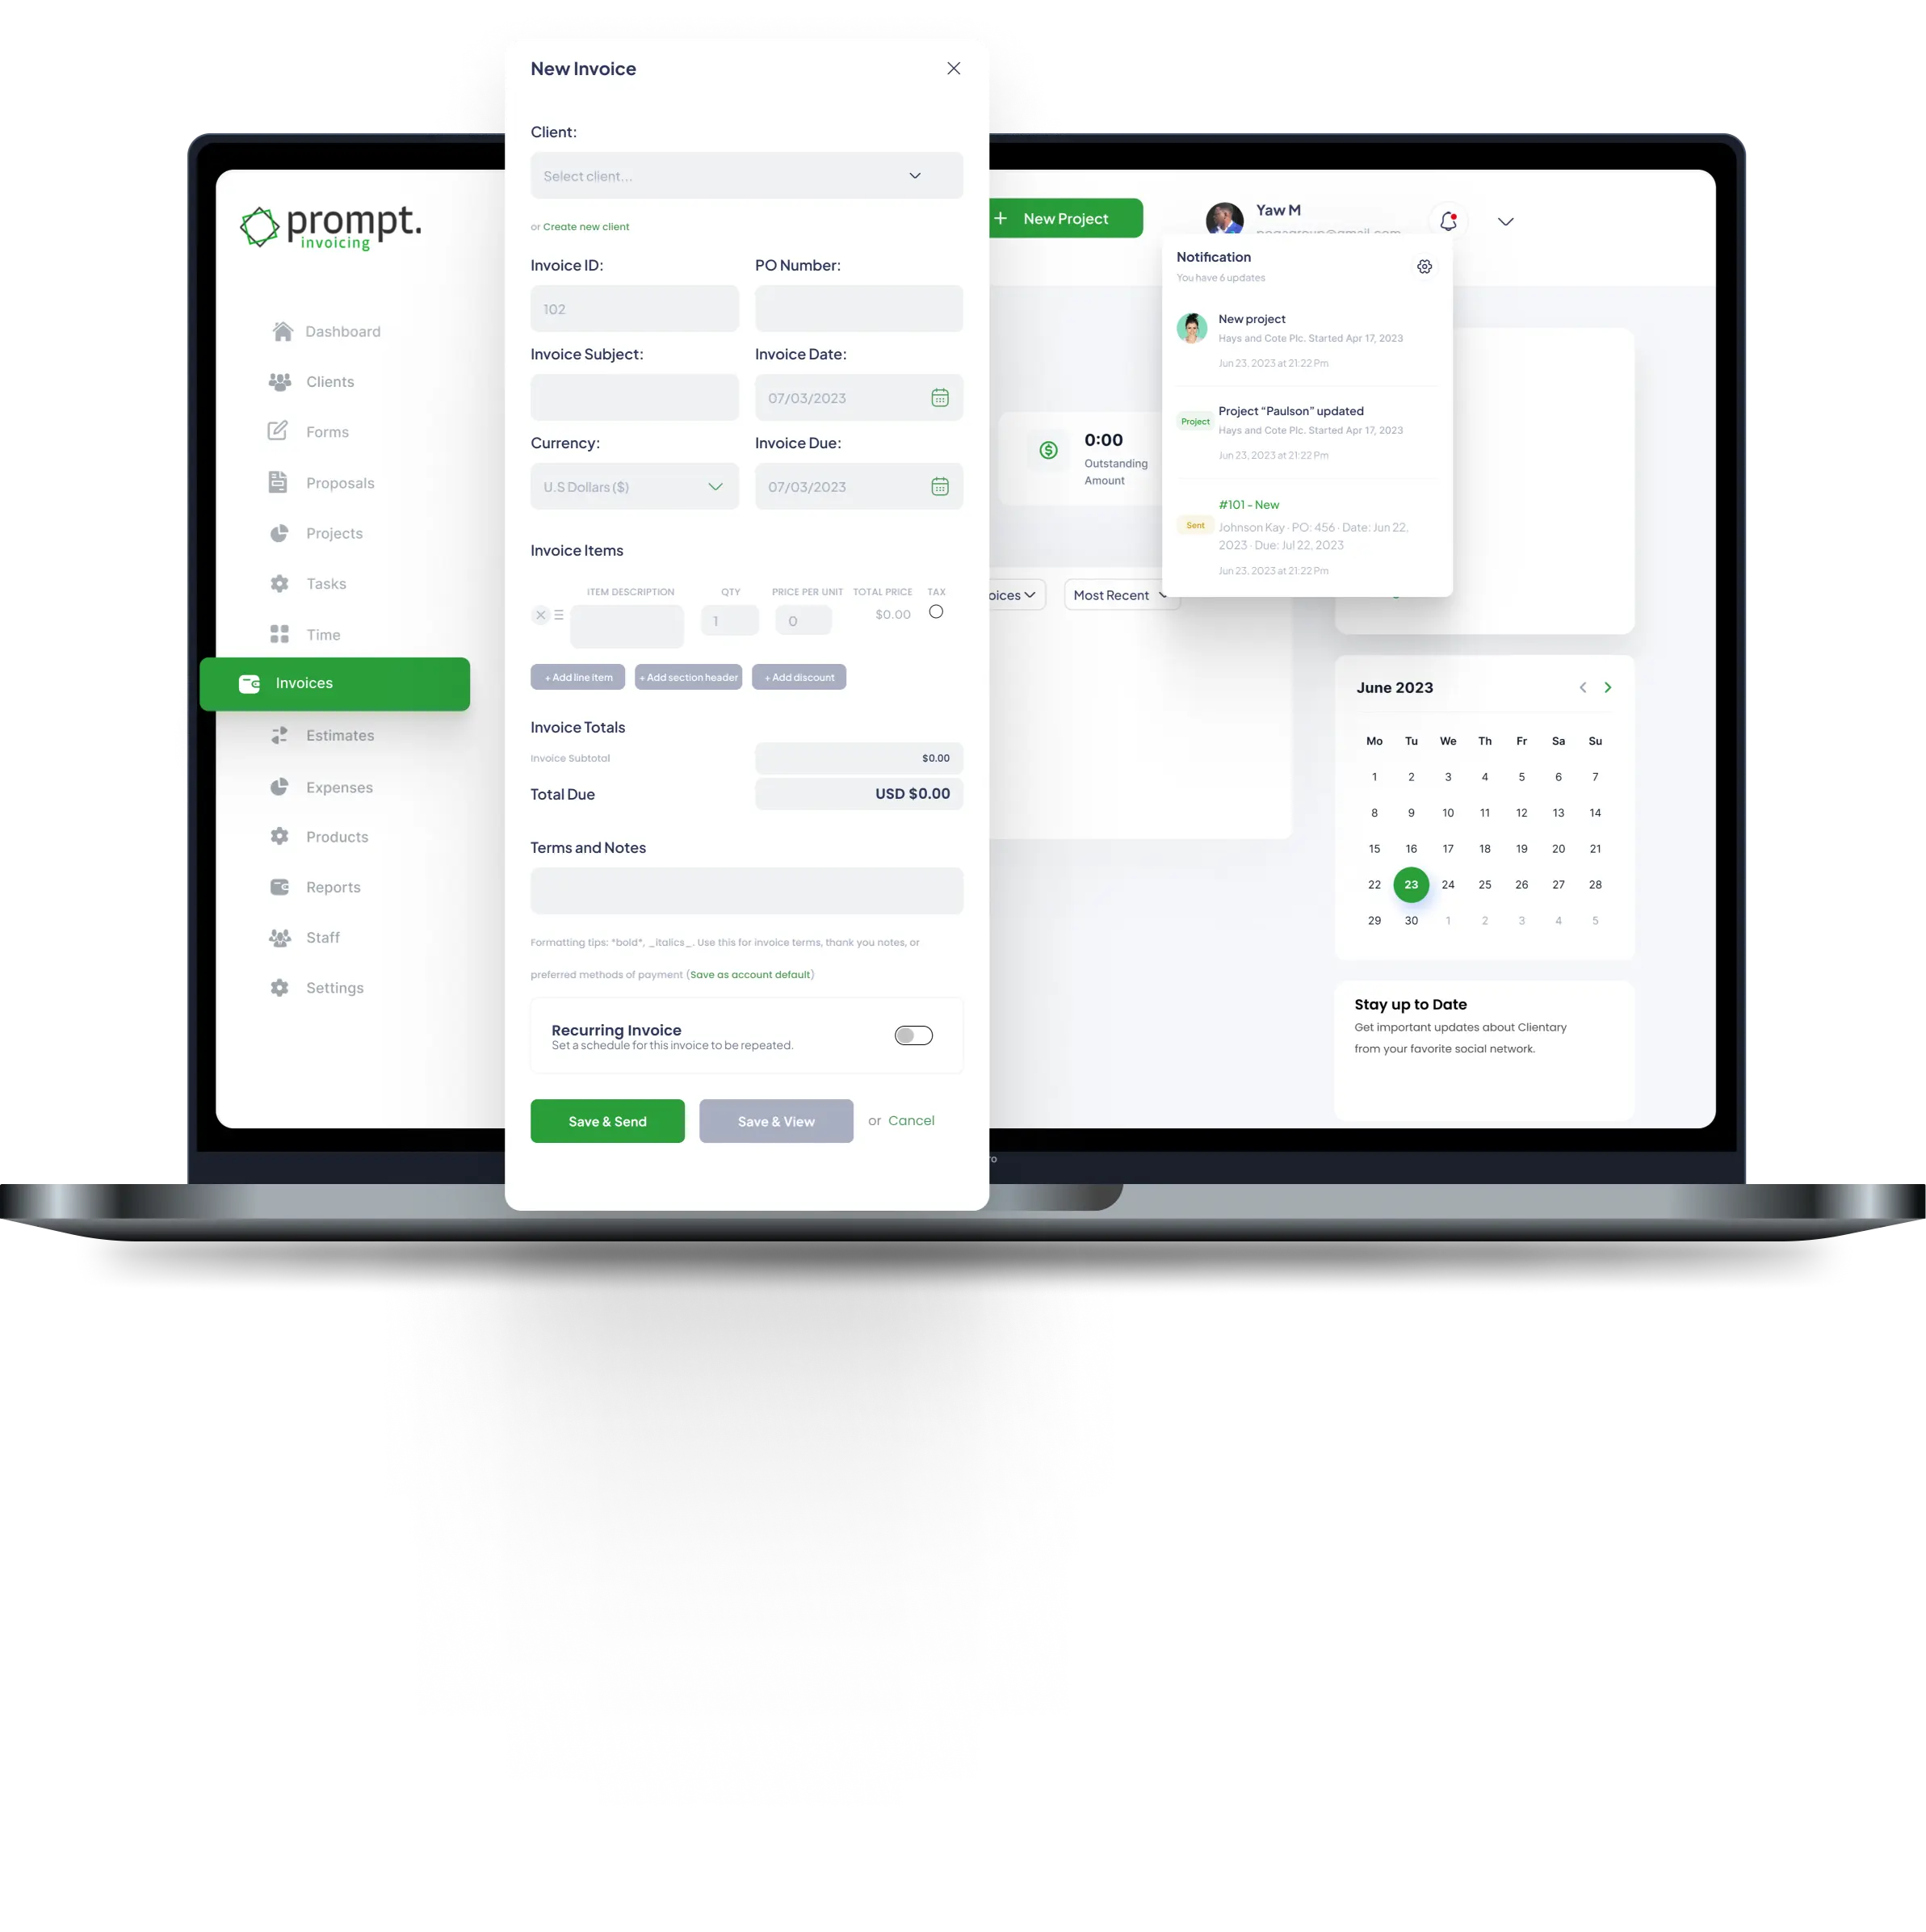
Prompt Integrated is built to give Ghanaian growing businesses the financial visibility and operational organisation they need to scale with confidence — with invoicing, expense management, payroll, and project management all in one platform. Get started with Prompt Integrated today.


Leave A Comment